You're guessing at the checkout.
One card catches ads, software, inventory, shipping, and fuel, even when a different card would earn double on some of them.
A one-page routing guide, so every expense has an obvious home.
For businesses with big monthly bills
Your business pays the same big bills every month. The right card turns each one into travel, cash back, or flexible points, usually with just one or two cards. No extra spending. No revolving debt.
✦ Flip Your Points ✦
| Monthly expense | Today | Flipped |
|---|---|---|
| Inventory & supplies $7,000 · stays at 2% | $140 | $140 |
| Online advertising $3,500 · moves to 4× | $70 | $140 |
| Software & subscriptions $1,500 · moves to 4× | $30 | $60 |
| Fuel & everything else $3,000 · stays at 2% | $60 | $60 |
2% cash back · 4× = 4% cash or ~6% in travel
Illustrative example, not a client result, quote, or guarantee. Points valued at 1¢ for cash and 1.5¢ for travel; before any welcome offers. Actual results vary by spending, merchant coding, card terms, and eligibility.
The problem
When the same bills hit every month, the card they land on makes all the difference. You don't need a wallet full of cards: the right one or two, matched to where your money goes, pays you back on every one of those bills, month after month.
One card catches ads, software, inventory, shipping, and fuel, even when a different card would earn double on some of them.
A one-page routing guide, so every expense has an obvious home.
Transfer partners, category caps, annual fees. Every "best business card" list was written for someone else's business.
I do the homework against your real spend and hand you a plan that takes minutes a month.
You carry the risk and make payroll. On one flat-rate card, a real share of the value you create never comes back to you.
The same spend, routed well, comes back as flights, hotel nights, or cash.
Built for businesses with high recurring spend
How it works
Twelve quick questions, about two minutes. You'll see right away whether your spending holds enough value to be worth chasing. Free, with no logins.
A short form with your cards and rough monthly spend by category. No statements, logins, or account numbers, ever. Then one 30-minute call with me about your goals and upcoming purchases.
Within 7 business days of our call: a verdict on your current cards, what to keep or change, the after-fee math, a one-page routing guide, and next steps. Questions afterward? Send them in one email within 14 days.
A worked example
Here's the routing guide a Blueprint might give the same $15,000-a-month business from the top of the page. It's illustrative, not a client result.
| Business expense | Use this card | Why |
|---|---|---|
| Online advertising | New 4× card | 4 points per dollar instead of 2% cash |
| Software & subscriptions | New 4× card | Same 4× category; set it once on autopay |
| Inventory & supplies | Your 2% card | Rarely earns a bonus anywhere, so 2% is hard to beat |
| Fuel | Your 2% card | A third card would add about $120 a year: not worth the hassle |
| Everything else | Your 2% card | Best simple everyday return |
When I'd tell you not to switch
Same business, but only $1,000 a month in advertising and software?
The new card would earn about $240 more a year than the 2% card, then charge a $375 fee. That's −$135. My recommendation would be to keep exactly what you have, and the guarantee means you'd get your money back.
Today
One 2% cash-back card, no annual fee
Earns today$3,600/yr
Recommendation
Keep the 2% card. Add one card that earns 4× on advertising and software.
Taken as cash (1¢/pt)+$825/yr
Redeemed for travel (~1.5¢/pt)+$2,025/yr
The plan, and the guarantee, are built on the conservative cash figure. Travel value is upside if you want it.
Considered and rejected
Illustrative example only. The 4× card, its $375 fee, and point values are assumptions for the math; real recommendations depend on your spending, eligibility, current card terms, merchant coding, and reward preferences.
Who it's for
Carrying a balance? Pay it down first. Interest wipes out rewards fast, and the free score will tell you the same thing.
Your points nerd
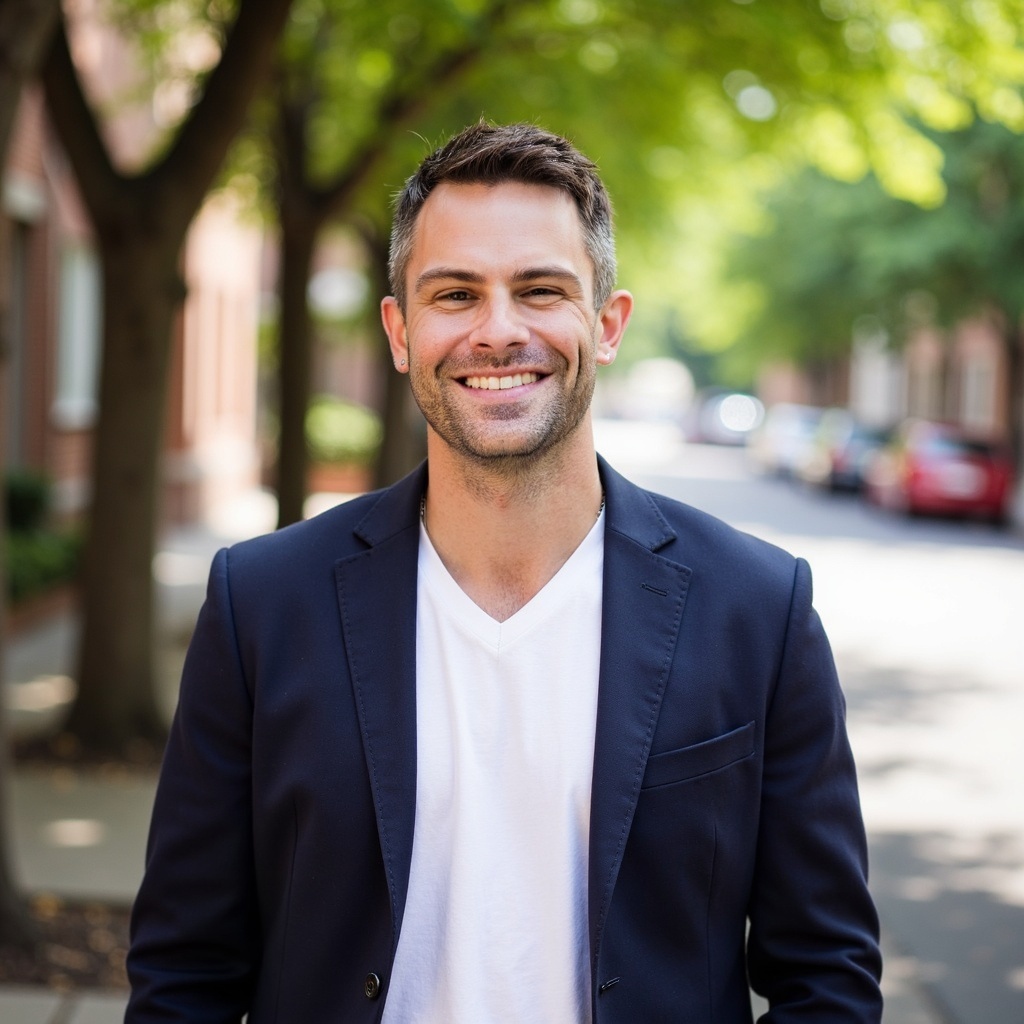
Joshua King
Founder · Flip Your Points
I'm a business owner and investor myself. I've used intentional card and rewards strategies to turn spending my family and businesses were already doing into flights, hotels, rental cars, and cash-equivalent value.
I built Flip Your Points for owners who want that value without turning points into a second job.
Years inside the programs that matter: American Express, Chase, Capital One, Citi, and Bank of America, plus Delta, United, Hilton, and IHG.
"I'm not the biggest spender in the room. I'm the one who went deepest on one question: how do you make every dollar of business spend earn more?"
Pricing
The regular price is $500. My first 10 clients pay $250, because I'm early and I'd rather earn your trust with results than charge for a track record I haven't built yet.
Everything included
Founding-client pricing covers one owner and one business; multiple entities or owners are quoted separately. Conservative first-year value is measured against your current card setup as documented on our call, after any new annual fees and payment surcharges, with points at their cash-out value and before welcome offers. Claims are due within 30 days of delivery. Rewards values are estimates and vary with spending, merchant coding, card terms, and eligibility. See the full terms.
FAQ
Then that's your answer, and a useful one: you'll know you're not leaving money on the table. If the Blueprint doesn't find at least $500 in conservative first-year value, you get your money back.
The regular price is $500. My first 10 clients get it for $250 because I'm early, and I'd rather earn your trust with real results than charge for a track record I haven't built yet. In return, I'll ask for honest feedback after delivery.
No, never. You'll fill out a short form with the cards you use (names only) and rough monthly spend by category. I don't ask for statements, logins, account numbers, or access to anything.
A credit-card application may affect your credit, and approval is never guaranteed. Your Blueprint explains what to consider, but whether to apply is always your call.
No, and most clients don't. Often the best move is one new card, or none. Recommendations are prioritized so you decide how far to go.
Flip Your Points is independent and is not a bank, lender, card issuer, or financial advisor. It is not affiliated with or endorsed by any issuer, airline, or hotel brand. Flip Your Points may receive compensation if you apply through certain links. That compensation does not determine which cards are evaluated or recommended, and some recommended products provide no compensation.
Get started
Twelve quick questions, about two minutes. You'll see your result right away, with an honest answer on whether a Blueprint is worth it for you. No logins, no obligation.
Run my numbersQuestions first? Email ask@flipyourpoints.com. I reply within one business day.